Digital Agency

Page Title Shape 1
Page Title Shape 2
Page Title Shape 3

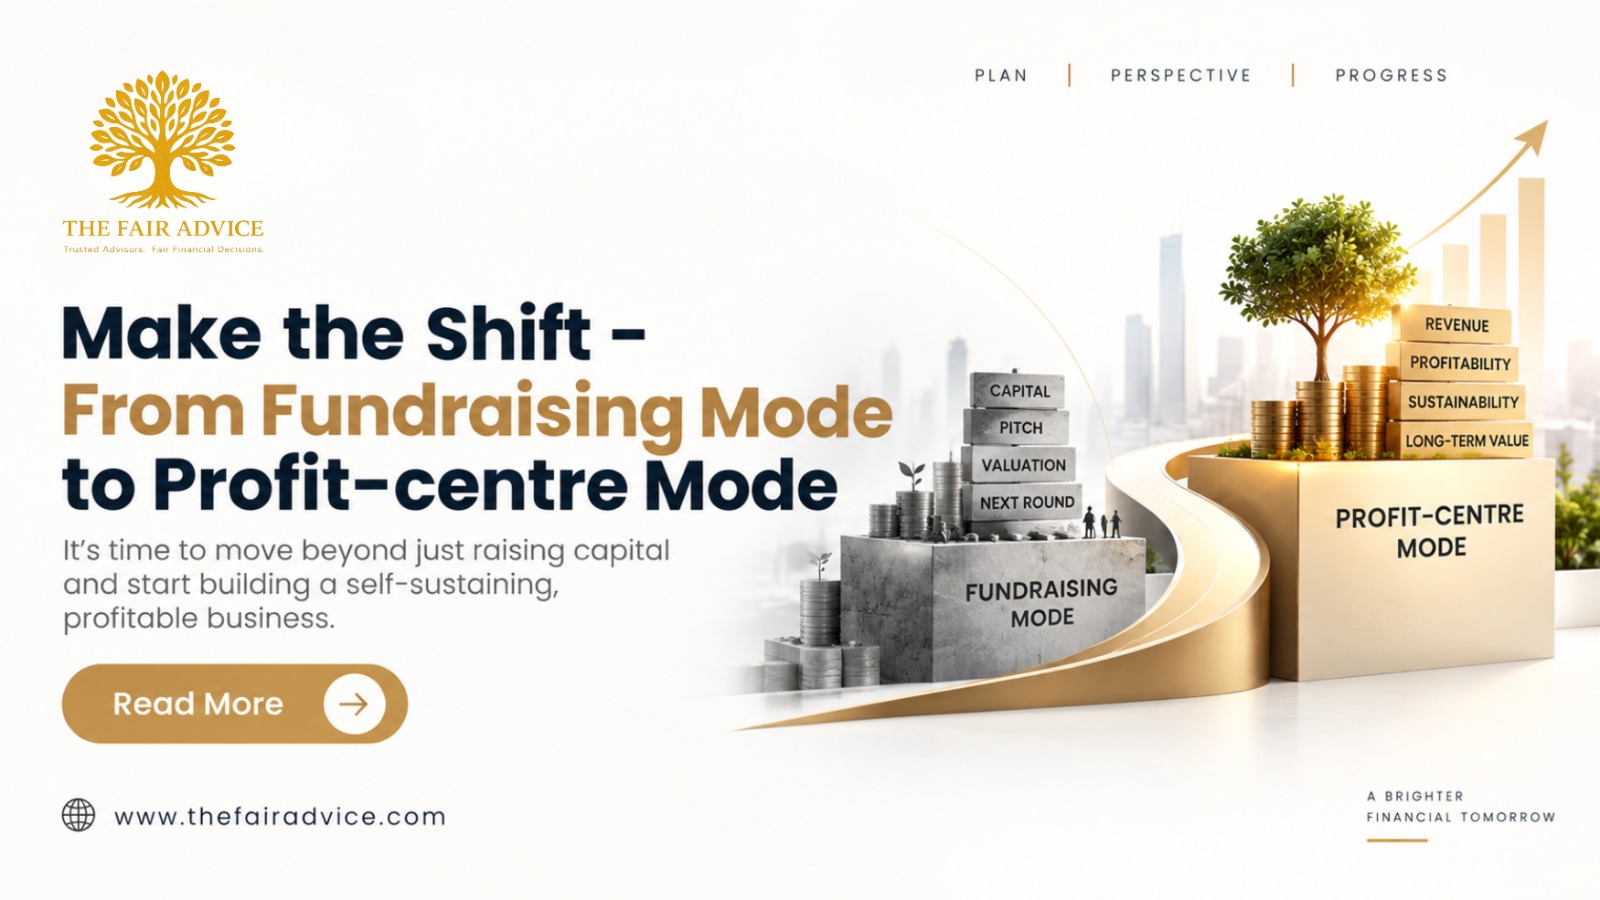
Make the shift – From Fundraising Mode to Profit-centre Mode

Make the shift – From Fundraising Mode to Profit-centre Mode Every founder I’ve sat with at some point asks the same question, usually earlier in the business than it should come up: who should I raise from next. Rarely do they ask the question that actually decides whether the business survives: how do I make this thing throw off cash on its own. Those are two different games. One is about convincing someone else your business will be worth more later. The other is about making sure it’s worth something right now, in cash, this quarter, without anyone else’s money in the account. For most businesses, chasing the first at the expense of the second has quietly become the more dangerous habit.   The funding era that just ended For most of the last decade, growth was the number everyone cared about. Profit was the thing you’d get to eventually. Capital was cheap enough that investors paid up for scale, not sustainability, and a founder who spent a pitch meeting talking about margins came off sounding a little old-fashioned next to one talking about taking over the category. These days it’s a different story. India’s startup funding actually dropped nearly 39% in 2025. Nobody should be surprised why: investors quietly shifted their attention from “how fast is this growing” to “does this actually make money.” You can see the same shift playing out well beyond India too. Funding cycles have gotten tighter and harder to predict, and being efficient with capital has stopped being a nice-to-have. This isn’t a temporary correction; founders just need to wait out. It’s a reset in what actually gets rewarded. And the businesses that were built to survive it were never the ones optimized for the next funding round in the first place. What “profit centre” actually means A profit centre isn’t just a business that happens to make money. It’s a business built, deliberately, so that revenue clears costs on its own terms, without needing a fresh round of capital to keep the lights on, without every strategic decision running through the lens of “will this help our next valuation conversation.” The distinction matters because these two models optimize for genuinely different things. A funded business optimizes for speed and scale, often before the unit economics are settled. A bootstrapped, profit-first business grows on a different clock entirely. Slower, usually. Nobody’s throwing millions at ads to buy growth they haven’t earned yet. But go through a rough patch, and that’s exactly when you see the difference: the funded competitor is panicking about runway, and the bootstrapped one is just… still there, doing the same thing it was doing before. That resilience isn’t a soft benefit. It’s the entire point. When a funded business hits a rough quarter, its options are constrained by whoever holds the board seats. When a profit-centre business hits a rough quarter, it has options, because it built its own runway instead of renting one. The evidence is no longer anecdotal Skeptics used to treat “profit over funding” as a nice idea that doesn’t survive contact with real competition. That argument gets harder to make every year. Zoho crossed ₹12,000 crore in annual revenue in FY25, the first Indian bootstrapped software company to reach that scale, without ever taking venture money. Zerodha converted roughly ₹9,372 crore of FY24 revenue into ₹5,496 crore of profit, a margin most funded fintechs chasing growth can’t get close to. These aren’t fringe examples anymore. They’re the businesses other founders are now studying. And it’s not just the headline names. Startup lender Capchase pulled data recently and found something founders don’t expect: bootstrapped businesses are keeping pace with venture-backed ones on growth, while spending roughly a quarter as much to land each customer. CB Insights has come to a similar place from a different angle. Companies that never took outside money tend to stick around longer and get to real, sustained profitability more often, and they’re about three times as likely to be profitable within three years compared to their VC-backed peers. The efficiency gap alone should stop most founders mid-pitch-deck. If you can hit similar growth for a quarter of the acquisition spend, the question isn’t whether you can afford to skip the raise. It’s whether you can afford not to. What chasing investors actually costs you None of this is an argument that outside capital is always wrong. Some businesses, genuinely capital-intensive ones, ones facing a real land-grab moment, need it. But most founders never run the honest cost-benefit on what a raise actually takes from them. Dilution compounds quietly. Every round gives away a slice of the business that never comes back. Founders who bootstrap to a strong outcome routinely end up personally far wealthier than funded peers at similar exit values, simply because they never diluted their equity along the way. Control shifts the moment the money lands. A funding round isn’t just capital. It’s a new voice in every major decision, a growth trajectory you’re now accountable to on someone else’s timeline, and a fund-return mandate that pushes founders toward outcomes large enough to matter at fund scale, sometimes faster and riskier than the business’s actual market position calls for. Burn becomes a habit you can’t easily break. Funded companies are working against a runway with a clock on it, and that clock changes behavior. Marketing spend creeps up, hiring speeds up, and suddenly you’re okay paying more to land a customer than you would’ve a year ago, because the goal quietly shifted from making money to owning the market. That posture works fine while the capital keeps flowing. It becomes a liability the moment it doesn’t. None of these costs show up on the term sheet. They show up eighteen months later, in a board meeting, when growth has slowed and the same burn rate that used to look like ambition now looks like exposure. Making the shift: from fundraising mode to profit-centre mode This isn’t only a message
Read More

The Tax Provision That Once Turned a Property Sale Into a Startup/MSME Stake And Why It Deserves a Second Life

Every so often, a provision quietly leaves the tax code and almost nobody notices until they go looking for it and find nothing there. Section 54GB is one of those. For sellers in the know, and for a certain kind of founder trying to raise capital, it used to be genuinely useful. Then it lapsed, and it stayed lapsed, carried forward into no subsequent version of the law, including the brand-new Income Tax Act, 2025. I want to walk through what it actually did, because it’s worth remembering, and because the case for bringing it back with a few sensible fixes is stronger now than it was when it disappeared. What Section 54GB used to do Sell a residential house or a plot of land, and the reflexive move has always been to buy another house and shelter the gain under Section 54. Section 54GB offered a genuinely different path: individuals and HUFs could claim the same exemption by investing the net sale proceeds into equity shares of an eligible startup or SME instead. The mechanics were specific, and deliberately so: The net sale consideration had to go into subscribing to equity shares of an eligible company, before the income tax return filing due date. The investor needed to end up holding a meaningful stake; the eligibility threshold moved around a bit over the years, but it consistently required real skin in the game, not a token allocation. The company then had roughly a year to deploy those funds into new assets supporting its business, new plant and machinery, for a manufacturing-oriented company, or computers and software for an eligible startup. The company had to genuinely qualify: recognized startup or MSME status, specific incorporation windows, and exclusion from sectors like real estate, trading, and financial services. Put money in, get a proportionate exemption on the gain. Full reinvestment, full exemption. It was a straightforward trade: redirect capital that would otherwise have gone into another property, or into the tax department, straight into a business that needed it.   Why it mattered more than its adoption numbers suggest The honest truth is that even while it was active, this provision was barely used. Awareness was the biggest problem. Section 54 dominated the conversation the moment a property sale came up, and advisors rarely extended the discussion to an equity alternative most of them had never had a reason to mention. But the handful of transactions that did use it point to something worth taking seriously: it created a direct, tax-efficient bridge between exactly the kind of capital that HNIs and family offices sit on proceeds from a property sale and exactly the kind of funding gap that early-stage manufacturing and MSME-adjacent startups struggle with the most. Not venture capital chasing a category. Not a bank loan requiring collateral the startup doesn’t have. A property seller with real proceeds, and a real tax incentive, choosing to back a business instead of buying another asset that mostly just sits there. That’s a genuinely different capital channel than most of what the startup funding conversation in India usually centers on. What actually happened to it Section 54GB stopped applying to any residential property transfer made after 31 March 2022. It wasn’t dramatically repealed; it simply wasn’t extended again, the way it had been extended several times before, going all the way back to its original 2017 cutoff. And when the Income Tax Act, 2025 was drafted, replacing the 1961 Act altogether, Section 54GB didn’t make the cut. It has no equivalent number in the new Act. It isn’t paused. It’s gone. For anyone selling a residential property today, that startup-investment route to a capital gains exemption no longer exists. The available alternatives reinvesting in another house under the new Act’s renumbered Section 84 (formerly Section 54), or into specified bonds under Section 85 (formerly 54EC), cover other needs, but neither one does what 54GB did: connect a property sale directly to equity in a startup or MSME. Why this is worth arguing for, not just noting Here’s where I’d push back on treating this as a historical footnote. India’s startup and MSME ecosystem hasn’t gotten less capital-hungry since 2022; if anything, the funding gap for early-stage manufacturing and MSME-adjacent businesses, the exact category 54GB was built for, has become a more visible policy concern, not a less visible one. Removing one of the only tax provisions that directly incentivized individual capital to flow into that gap, at a moment when that gap hasn’t closed, is a strange thing to have let quietly expire. A reinstated version of this provision, done with a few deliberate refinements, could do more than the original ever did: Widen who qualifies on the company side. The original was fairly narrow about excluded sectors and company structure. A revived version could extend more deliberately to MSMEs formalizing under Udyam registration, not just DPIIT-recognized startups, which would substantially widen the pool of businesses that could receive this capital. Simplify the compliance load. Tracking fund utilization within a year, monitoring a five-year lock-in on two separate assets, verifying ongoing eligibility  this was genuinely heavy relative to the size of many of these transactions. A cleaner, more automated compliance framework would remove one of the real reasons advisors avoided recommending it. Fix the awareness problem structurally, not just rhetorically. If this comes back, it should come back paired with something like mandatory advisor disclosure at the point of a large property sale  the same way certain other reinvestment options are supposed to be flagged. A provision nobody knows about might as well not exist, and that was arguably 54GB’s biggest failure even while it was technically in force. Reconsider the minimum stake threshold. Requiring a large ownership stake made sense as an anti-abuse measure, but it also excluded HNIs who wanted meaningful, but not controlling, exposure. A tiered structure with a larger exemption for larger stakes, some exemption even at a lower threshold, could bring in a wider set of investors without
Read More

A client sold ₹80 lakh worth of mutual funds. Made a ₹50 lakh profit. Paid zero tax on it. Legally.

Somewhere in most people’s portfolio review, there’s a moment where the advisor says “you’ll owe tax on that gain” and the conversation just… stops there. Nobody asks the next question. And the next question is usually worth more than the rest of the meeting combined. If you’ve booked long-term gains on mutual funds, shares, or gold this year, there’s a legal route to defer or wipe out the tax on them entirely. It’s called Section 54F, and in my experience, it gets checked against maybe one portfolio in twenty. Why this even matters right now From FY 2025–26, most long-term capital gains are taxed at a flat 12.5%, with indexation gone. That sounds like a simplification, and technically it is. But it also means a big gain produces a big, immediate tax bill; there’s no cost-inflation adjustment softening the blow anymore. Sell a large equity or mutual fund position after a good multi-year run, and the number on your tax outflow is not going to be small. The advisor conversation, when it happens at all, tends to confirm the rate and stop. Almost nobody follows up with: is there a house purchase somewhere in your near future planned, half-considered, or one you hadn’t even connected to this sale that could turn this liability into a partial or full exemption? Section 54F exists exactly for this gap. And it’s written more broadly than most people assume: land, listed shares, mutual fund units, gold, basically any long-term capital asset other than a residential house itself. How it actually works Here’s the mechanics, stripped down: It covers long-term capital gains on any asset except a residential house, shares, mutual funds, land, gold, all in scope. Only individuals and HUFs can use it. Companies, LLPs, and firms are out. On the date you sell the original asset, you can’t already own more than one residential house (other than the new one you’re buying). The new property has to be purchased within one year before or two years after the sale — or, if you’re constructing rather than buying, completed within three years. The exemption scales with how much of the net sale consideration you reinvest. Put in all of it, get the full exemption. Put in half, get roughly half. There’s a ₹10 crore cap on the gain eligible for this exemption that’s been the rule since April 2024, and it’s still in force for this financial year. Can’t get the house ready in time? Park the money in a Capital Gains Account Scheme before your return filing deadline, and you still get the exemption, provided you use the funds within the prescribed window. One detail worth sitting with: the exemption is based on how much of the net sale consideration goes into the house, not just how much of the gain does. If you sold ₹80 lakh worth of gold and made a ₹50 lakh gain, you need to reinvest close to the full ₹80 lakh to get the whole exemption, not just the ₹50 lakh profit. People trip over this constantly. Where I keep seeing the same three mistakes Sequencing, mostly. Someone sells the asset, pays the tax, and only a year later, sometimes longer, starts thinking about buying a house. By then the reinvestment window is either uncomfortably tight or already shut. The exemption rewards planning the sale and the purchase together. Treat them as two separate financial decisions and you’ve usually already lost the benefit before you knew it existed. Confusing 54 with 54F. Section 54: property sold, property bought is the one everyone’s heard of. Because it’s more familiar, a lot of investors never realize that portfolio gains from shares, mutual funds, or gold qualify under the related 54F provision, as long as the proceeds go into a house. Different asset sold, same underlying idea. The house-ownership trap. If you already own a second residential property, even one sitting empty, even one you barely think about, you can find yourself disqualified from this route entirely. There’s a well-known case, Lata Goel’s, where the tax department tried to argue that owning two separate floors of one building counted as owning two houses; the high court disagreed. But that’s the kind of thing that ends up in court precisely because it’s easy to get wrong without checking first. A practical way to run this before you sell Before you execute a large sale of long-term equity, mutual fund, or gold holdings, three questions are worth fifteen minutes with your CA: Is a residential property purchase realistically on the horizon, within the reinvestment window? Does your current residential property ownership actually fit the 54F conditions? Can the sale be timed to line up with the property purchase, rather than happening on its own schedule? None of this asks you to restructure your investment strategy. It just asks you to treat a large capital gains event as something you plan, rather than something you execute first and explain to your tax preparer later. One thing worth flagging on timing Tax provisions like this one get renumbered and revised periodically, and this is actually happening right now. Under the newer Income Tax Act, 2025, which starts applying to income earned from April 2026 onward, Section 54F has effectively been renumbered as Section 86. The substance hasn’t changed. The number has. Which is exactly the kind of detail that trips people up if they’re working from an old article or an old advisor conversation. Always check the current section number, cap, and timeline against the law as it stands, and against a professional who’s looked at your specific situation, not a generic guide. What to actually do Before selling significant long-term mutual fund, share, or gold holdings, check whether a house purchase could realistically be sequenced within the reinvestment window. Know exactly how many residential properties you currently own. This exemption has specific, unforgiving conditions tied to that number. If the property isn’t ready when you sell, look at the Capital Gains Account Scheme
Read More

GIFT City for NRIs: Your Complete 2026 Investment Guide

GIFT City for NRIs: Complete Investment Guide 2026 Why This Matters to You If you’re an NRI, you’ve likely faced this frustration: investing in India means dealing with complicated repatriation rules, multiple regulators, and confusing tax treatment. Want to invest abroad from India? You hit the LRS limit quickly, face 20% TCS, and still manage currency risk. GIFT City changes this equation. Think of it as India’s answer to Dubai or Singapore—a financial zone that’s technically in India but operates like an offshore hub. You get the best of both worlds: access to Indian growth stories, global investment products, and all of it in US dollars with simplified tax treatment. But here’s the catch: GIFT City comes with its own rule book. FEMA treats it differently. RBI has special guidelines. Tax treatment varies based on how you fund your investments. Get it wrong, and you could face repatriation blocks, tax notices, or compliance headaches. This guide cuts through the complexity and tells you exactly what you need to know. What Makes GIFT City Different GIFT City (Gujarat International Finance Tec-City) in Gandhinagar is India’s first and only International Financial Services Centre (IFSC). The government treats it as a “deemed foreign territory” under FEMA regulations—which means different rules apply compared to mainland India. The regulator here is IFSCA (International Financial Services Centres Authority), not SEBI, RBI, or IRDAI individually. This unified regulation means faster approvals, more flexibility, and products that don’t exist in regular India. Key advantages: Investments and transactions in US dollars 10-year tax holiday for IFSC entities (Section 80LA) Full repatriation allowed when funded correctly Access to global products alongside Indian ones Extended trading hours covering US, Europe, and Asia Who can invest: NRIs, OCIs, Resident Indians (via LRS), and foreign investors. Investment Options Available to NRIs 1. Mutual Funds and ETFs in GIFT City GIFT City hosts mutual funds from Indian and international asset managers offering everything from Nifty index funds to global equity funds tracking S&P 500 or Nasdaq. How it works for NRIs: Fund using NRE/FCNR accounts or fresh foreign remittance All transactions in USD Fully repatriable when funded through repatriable sources No RBI approval needed (treated as portfolio investment under FEMA) Tax treatment: Equity funds (>12 months): 10% LTCG above ₹1 lakh, or claim DTAA benefit Debt funds: 20% with indexation for LTCG, or DTAA rate TDS applies; submit Form 10F + Tax Residency Certificate to claim treaty benefits Why this matters: IFSC funds can be more tax-efficient than regular Indian mutual funds, especially for categories benefiting from Section 80LA. Watch out for: Not all GIFT City funds automatically give tax exemption. Check fund structure carefully. Also, declare these investments in your country of residence. 2. Alternative Investment Funds (AIFs) GIFT City AIFs give you access to private equity, venture capital, real estate, and hedge fund strategies with more regulatory flexibility than onshore Indian AIFs. Key points: Minimum investment: Usually USD 150,000+ Fully repatriable if funded correctly Pass-through taxation applies TDS depends on income type Risk level: High. These are illiquid, long lock-in periods, suitable only for sophisticated investors with surplus capital. 3. Stock Exchange Trading NSE IFSC and India INX operate in GIFT City, offering: Indian derivatives (Nifty, BankNifty futures/options) Currency derivatives Global stocks via Unsponsored Depository Receipts What NRIs should know: Trading in USD (creates currency exposure) Extended trading hours (21+ hours daily) Derivative income = business income (not capital gains) Fully repatriable profits when funded repatriably Common mistake: Assuming GIFT City equity derivatives get capital gains treatment. They don’t—it’s business income taxed at slab rates. 4. Banking Products (IBU Deposits) Indian and foreign banks run IFSC Banking Units (IBUs) offering foreign currency deposits with competitive rates. Advantages over regular NRE deposits: RBI interest rate caps don’t apply here Often get higher USD deposit rates Fully repatriable (principal + interest) Tax treatment: Interest income: Taxable in India for NRIs TDS: 30% unless you claim DTAA benefit Submit Tax Residency Certificate + Form 10F for lower treaty rate 5. Insurance Products Life and health insurance companies offer USD-denominated policies in GIFT City. Benefits: Premiums and claims in foreign currency Maturity proceeds tax-free under Section 10(10D) if conditions met For UAE NRIs with India-UAE DTAA: potentially nil TDS on maturity How Resident Indians Can Invest (LRS Rules) If you’re a resident Indian, you can invest in GIFT City but only through the Liberalized Remittance Scheme (LRS). Critical facts: LRS limit: USD 250,000 per financial year (no expansion has happened) TCS: 20% on amounts above ₹7 lakh for investment purposes Must use purpose code S0001 when remitting All LRS transactions reported to RBI by your bank Tax implications: All GIFT City income taxable in India Must disclose in ITR Schedule FA (foreign assets) Capital gains taxed per holding period and asset class If you paid tax abroad, claim foreign tax credit under Section 90/91 Common mistakes: Thinking GIFT City investments don’t count toward LRS (they do), or not factoring in TCS cost when calculating returns. Tax Benefits: What Actually Applies to You Section 80LA Tax Holiday This 10-year tax exemption applies to IFSC entities (fund houses, banks), not directly to you as an investor. But you benefit indirectly through lower costs and better returns. Your Tax Treatment as NRI Equity investments: LTCG (>12 months): 10% above ₹1 lakh, or DTAA rate STCG (≤12 months): 15%, or DTAA rate Debt investments: LTCG (>36 months): 20% with indexation, or DTAA rate STCG: 30%, or DTAA rate Derivative trading: Business income at 30% DTAA Considerations by Location UAE NRIs: No capital gains tax in UAE; India taxes apply. Net result: you only pay Indian tax. US NRIs: US taxes your global income. Claim foreign tax credit for Indian taxes paid. Watch out for PFIC rules on certain funds. UK NRIs: UK taxes worldwide income. Claim foreign tax credit. Consider timing exits around UK tax year. Singapore NRIs: No capital gains tax in Singapore. India-Singapore DTAA favorable for portfolio investments. Bottom line: You must evaluate tax in BOTH countries.
Read More