


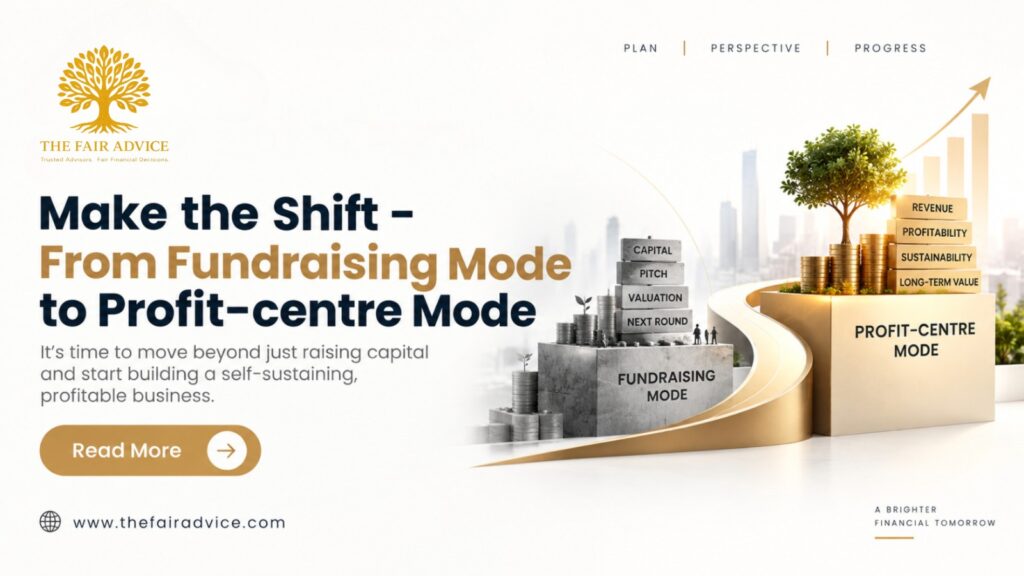
Make the shift – From Fundraising Mode to Profit-centre Mode
Every founder I’ve sat with at some point asks the same question, usually earlier in the business than it should come up: who should I raise from next. Rarely do they ask the question that actually decides whether the business survives: how do I make this thing throw off cash on its own.
Those are two different games. One is about convincing someone else your business will be worth more later. The other is about making sure it’s worth something right now, in cash, this quarter, without anyone else’s money in the account. For most businesses, chasing the first at the expense of the second has quietly become the more dangerous habit.
The funding era that just ended
For most of the last decade, growth was the number everyone cared about. Profit was the thing you’d get to eventually. Capital was cheap enough that investors paid up for scale, not sustainability, and a founder who spent a pitch meeting talking about margins came off sounding a little old-fashioned next to one talking about taking over the category.
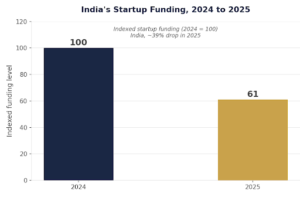
These days it’s a different story. India’s startup funding actually dropped nearly 39% in 2025. Nobody should be surprised why: investors quietly shifted their attention from “how fast is this growing” to “does this actually make money.” You can see the same shift playing out well beyond India too.
Funding cycles have gotten tighter and harder to predict, and being efficient with capital has stopped being a nice-to-have.
This isn’t a temporary correction; founders just need to wait out. It’s a reset in what actually gets rewarded. And the businesses that were built to survive it were never the ones optimized for the next funding round in the first place.
What “profit centre” actually means
A profit centre isn’t just a business that happens to make money. It’s a business built, deliberately, so that revenue clears costs on its own terms, without needing a fresh round of capital to keep the lights on, without every strategic decision running through the lens of “will this help our next valuation conversation.”
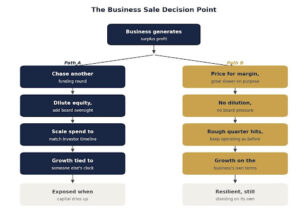
The distinction matters because these two models optimize for genuinely different things. A funded business optimizes for speed and scale, often before the unit economics are settled. A bootstrapped, profit-first business grows on a different clock entirely. Slower, usually. Nobody’s throwing millions at ads to buy growth they haven’t earned yet. But go through a rough patch, and that’s exactly when you see the difference: the funded competitor is panicking about runway, and the bootstrapped one is just… still there, doing the same thing it was doing before.
That resilience isn’t a soft benefit. It’s the entire point. When a funded business hits a rough quarter, its options are constrained by whoever holds the board seats. When a profit-centre business hits a rough quarter, it has options, because it built its own runway instead of renting one.
The evidence is no longer anecdotal
Skeptics used to treat “profit over funding” as a nice idea that doesn’t survive contact with real competition. That argument gets harder to make every year.
Zoho crossed ₹12,000 crore in annual revenue in FY25, the first Indian bootstrapped software company to reach that scale, without ever taking venture money. Zerodha converted roughly ₹9,372 crore of FY24 revenue into ₹5,496 crore of profit, a margin most funded fintechs chasing growth can’t get close to. These aren’t fringe examples anymore. They’re the businesses other founders are now studying.
And it’s not just the headline names. Startup lender Capchase pulled data recently and found something founders don’t expect: bootstrapped businesses are keeping pace with venture-backed ones on growth, while spending roughly a quarter as much to land each customer. CB Insights has come to a similar place from a different angle. Companies that never took outside money tend to stick around longer and get to real, sustained profitability more often, and they’re about three times as likely to be profitable within three years compared to their VC-backed peers.
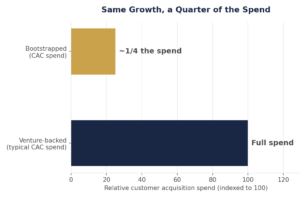
The efficiency gap alone should stop most founders mid-pitch-deck. If you can hit similar growth for a quarter of the acquisition spend, the question isn’t whether you can afford to skip the raise. It’s whether you can afford not to.
What chasing investors actually costs you
None of this is an argument that outside capital is always wrong. Some businesses, genuinely capital-intensive ones, ones facing a real land-grab moment, need it. But most founders never run the honest cost-benefit on what a raise actually takes from them.
Dilution compounds quietly. Every round gives away a slice of the business that never comes back. Founders who bootstrap to a strong outcome routinely end up personally far wealthier than funded peers at similar exit values, simply because they never diluted their equity along the way.
Control shifts the moment the money lands. A funding round isn’t just capital. It’s a new voice in every major decision, a growth trajectory you’re now accountable to on someone else’s timeline, and a fund-return mandate that pushes founders toward outcomes large enough to matter at fund scale, sometimes faster and riskier than the business’s actual market position calls for.
Burn becomes a habit you can’t easily break. Funded companies are working against a runway with a clock on it, and that clock changes behavior. Marketing spend creeps up, hiring speeds up, and suddenly you’re okay paying more to land a customer than you would’ve a year ago, because the goal quietly shifted from making money to owning the market. That posture works fine while the capital keeps flowing. It becomes a liability the moment it doesn’t.
None of these costs show up on the term sheet. They show up eighteen months later, in a board meeting, when growth has slowed and the same burn rate that used to look like ambition now looks like exposure.
Making the shift: from fundraising mode to profit-centre mode
This isn’t only a message for early-stage founders deciding whether to raise a seed round. It applies just as much to businesses that already took outside capital and now want to rebuild real financial independence.
Price for margin, not for market share. If your pricing strategy only works “once we hit scale,” it isn’t a pricing strategy. It’s a bet on a future round bailing it out.
Treat every hire as a cash decision, not a growth decision. Funded businesses hire ahead of revenue because the capital allows it. A profit-centre business hires behind revenue, on purpose, because that’s what keeps the business answerable to its own numbers instead of someone else’s timeline.
Build a cash buffer before you build a growth plan. A business with reserves can make deliberate decisions. A business without them makes desperate ones, and desperate decisions are exactly what send founders back to the fundraising table on worse terms than their last round.
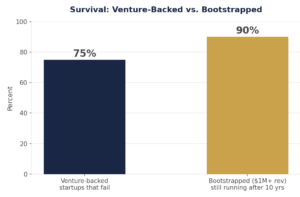
Measure yourself against your own P&L, not against the last funding announcement in your sector. The businesses posting the loudest raises aren’t necessarily the ones still around in five years. Something like three out of four venture-backed startups fail. Meanwhile, of the bootstrapped companies that actually get to $1M in revenue, most of them, roughly nine in ten, are still around ten years on. If you’re picking a number to build a strategy around, that one’s a lot more useful than last week’s funding headline.
Where the profit actually goes
Here’s the part founders chasing the next round rarely plan for: what happens to the cash once the business genuinely starts throwing it off. A profit centre that’s actually working generates surplus capital, and that surplus deserves the same discipline you applied to earning it in the first place. Leaving it idle in a current account, or plowing all of it straight back into the business without a plan, wastes the very independence you built by not raising.
This is where most founders are on their own, because it’s outside their operating expertise, and it’s exactly the gap The Fair Advice is built to close. Rather than defaulting to another fundraising conversation, business owners and HNIs generating real surplus can work with The Fair Advice’s verified, fiduciary advisors to put that capital into structured, principal-protected investment products, instruments designed to participate in market upside while managing the downside, so the cash a profitable business generates keeps compounding on its own terms, the same way the business itself was built.
The real argument
A funding round is a bet that someone else believes in your future enough to write a check. A profit centre is proof that your business doesn’t need that belief to keep existing. One of those is a story you tell investors. The other is a fact your bank statement confirms every month, whether or not anyone else is watching.
Build the thing that doesn’t need permission to survive.
If your business has reached the point of generating real, consistent profit and you’re now facing the next question, what to do with that capital, it’s worth a conversation before you default to reinvesting it all or raising another round. The Fair Advice connects business owners with verified, unbiased financial advisors and structured investment products built to grow surplus capital with real downside protection, so the profit you worked to build keeps working for you.
This article is for general information only and isn’t financial or investment advice. Structured products come with market-linked risk, and the exact terms depend on whoever’s issuing them. Worth talking to a qualified financial advisor before you put money into one.